



Credit Corp Group (ASX: CCP) shares are down 30% today. CCP shares slumped because the company admitted that it had paid the wrong price for a collection of US debts. Well, when interest rate cycles turn this can happen and there shouldn’t be all that much surprise that it has here. What worries much more than any one off hit to the profits is that there’s no assurance that the problem won’t continue. That is, that new debt purchases won’t suffer from the same problem.
The business itself is simple enough: “ Credit Corp Group Limited provides debt ledger purchase and collection, and consumer lending services in Australia and the United States. The company operates through three segments: Debt Ledger Purchasing – Australia and New Zealand; Debt Ledger Purchasing – United States; and Consumer Lending – Australia, New Zealand and the United States. The company offers debt sale, contingency and agency collection, local government debt recovery, and hardship and insolvency management services, as well as various loan products.”
Effectively, debt collectors. There’s a vibrant market in overdue debts, go buy a package of that, collect on it and make the profit difference between debt purchase price and collections. It’s a simple enough business but which has an inherent problem.
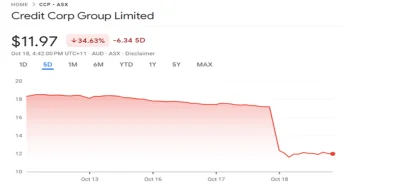
Credit Corp Group share price from Google Finance
The model obviously depends upon the price at which you buy the debt. It’s not the base interest rate that matters here - 3 or 5% at the Fed doesn’t make much difference. But the whole credit cycle does - in bad times a much greater portion of the debt is unrecoverable.
The announcement: “The impairment has arisen from a sustained deterioration in collection conditions. In releasing its FY2023 results on 1 August 2023 Credit Corp advised of increased US repayment plan delinquency over the final quarter. These conditions have persisted throughout the first quarter of FY2024, prompting a reassessment of the medium-term outlook for collections on the Company’s US PDL assets. The purchasing cohorts most affected comprise of assets acquired in FY2022 and FY2023.”
More Americans are struggling with debt now than when those debt books were bought. That means collection rates are lower, Credit Corp overpaid. Well, OK, that’s a one off hit, right? Sure $45 million, but a one off.
“Mr Thomas Beregi, CEO of Credit Corp, said that reduced market pricing should support the viability of continued purchasing. “Prices at which the FY2024 US investment pipeline has been secured should deliver Credit Corp’s target return in present conditions,” he said.”
Ah, but will it? Because if credit conditions continue to deteriorate as the cycle turns then are we certain that current distressed debt prices fully reflect future collection rates? They might well reflect current collection rates, but as with those 2022 and /3 purchases, do they reflect future?
That’s the real worry here and there’s also no real answer to it as yet. Therefore risk has risen - and as risk rises equity prices fall.
