



Cheche Group (NASDAQ: CCG) stock is down another 40%. CCG stock is therefore some 70% up on the pre-Spac combination price, also down 92% from its most absurd during the deal price. Which is the correct long term price, well, as we can see, that’s something still to be decided. We would very strongly suggest that the $200 peak isn’t it but other than that we’re happy to let other people work out what it should be.
The business line at Cheche: “Beijing Cheche Technology Co., Ltd. operates an online auto insurance platform. The company is based in Beijing, China.” Well, OK, it’s a bit more than that, it’s one of China’s leading online auto insurance marketplaces. But how much is that worth, really? The answer lies more in the details of the Spac, or Despac, deal than anything else.
When announced it was expected that the deal - with Prime Impact Acquisition I - would generate some $22 million in cash proceeds for Cheche. “Common stock financings and trust account balance expected to generate approximately $22.1 million in proceeds for Cheche”
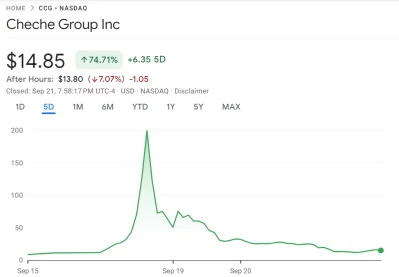
Cheche Group stock price from Google Finance
The problem seems to be that not that many of the Spac holders decided to stick around for the deal: “As of March 1, following an extension vote, the SPAC said 2,725,066 shares were redeemed, erasing about 41% of the remaining cash held in trust as of the Cheche deal announcement in January. That left the SPAC with about $48 million in trust. Further redemptions up to the completion vote last week reduced the trust to about $4 million.
At an enterprise value of $841 million, the deal was originally expected to bring Cheche about $68 million in gross proceeds. The final tally will be closer to $22 million.”
We’d suggest that this shows that the Spac route to market is a great deal less attractive than it was. Assuming that the reason to IPO is to raise capital then it’s a tactic - a strategy - that’s not really working any more. On the other hand, if the aim is simply to float in order to have paper to pay for things then it’s working just fine.
The outcome right now is that Cheche thought it had an enterprise value of $800 million and climbing, the current market capitalisation is $106 million. Ouch. So we can see why the vertiginous climb in the CCG stock price - to chase that enterprise value - but that’s not exactly how it has worked out, is it?
