


Iluka Resources (ASX: ILU) (OTCPK: ILKAF) is taking on a substantially risky project, the building of a rare earths refinery. We can think about this as being globally necessary - there's only the one major non-China one of those available at present - and so on. But that the industry would like to have it doesn't mean that it's going to be profitable for the company that builds it. Such refineries cost a lot - $1 billion is about the minimum - and will face substantial price risk over the decades of operation. After all, rare earth prices shot up in 2010, two major producers were financed as a result. Lynas then needed an almost entire recapitalisation and Molycorp actually went bust again. Two entrants into the global market was enough to crash prices again.
However, having said that it all depends. If it's possible to get other people to carry the downside risk, while being able to capture the upside, then the deal looks very different. This is what Iluka Resources seems to have been able to do. It's the Australian taxpayer carrying the downside risk, Iluka the upside of potential profit. Sorta a heads I win, tails you lose situation and that does change any idea of the net present value of the project.
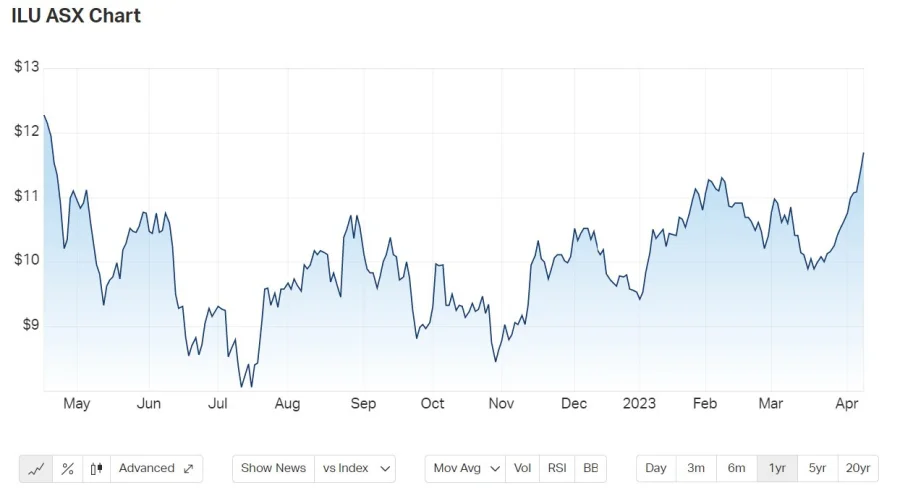
Iluka Resources share price from ASX
The detail is in this document: “Iluka will contribute cash equity of $200 million (provided on a 1:3 ratio basis with initial Critical Minerals Facility loan drawdowns); a $1,270 million2 equity-like contribution of the Eneabba stockpile; and funds deployed of $50 million for Phase 1 and Phase 2 plant and $20 million for the Phase 3 feasibility study. Commonwealth funding is via a $1,050 million non-recourse loan provided to RefineryCo under the Critical Minerals Facility, administered by EFA, plus a $200 million cost overrun facility if required. “
Iluka must put up some of the cash, that $200 million. But in real terms that's all - for the building of a $1 billion and above plant. Because that loan from the taxpayers is non-recourse. If the project fails then no one can come ask Iluka for the cash back. Yes, Iluka is contributing that stockpile of monazite and xenotime. However, to a reasonable approximation, if the processing plant isn't built then those two minerals have no - or at least near no - value. There's no one out there currently willing to process such minerals with the uranium and thorium levels they contain. They have value if the plant is built, don't if it isn't. It's the building of the plant that provides value to the stockpile. So, to be able to use the stockpile as a capital contribution to the cost of the plant is a very clever idea indeed.
It's also true that assuming the plant is built then it will be the only non-China plant willing to process those two materials. And there's no shortage of them from other mineral sands operations, no shortage at all.
We would still worry about the rare earths market itself, we're really quite certain (but this is of course an opinion, not a fact) that the market will move into oversupply soon enough. However, while the project might not succeed on that basis Iluka seems to have limited the downside risk extremely well.
