Gentrack Group (ASX: GTK) shares are up 29% today on the back of the results announcement. These results are pleasingly good - we might even employ the word stonking to describe them. It appears that supplying software to utilities in the ANZAC arena is a good business to be in.
The background here is that utilities are complicated organisations. They are, by their very nature, sprawling organisations and they live and die by capital investment and the subsequent maintenance of those assets. Tracking what there is, how well it's doing and when it needs to be repaired or replaced is thus key to the success of the utilities themselves. The management problems are also specific to this field - other types of companies simply don't face quite the same problems.
Utilities are also pretty slow moving organisations. It's in the nature of the business - water pipes put in today are likely still going to be in use in 50 years' time. So, becoming embedded in the management structure of a utility is going to be a long term business, a long term stream of income. This is exactly what Gentrack does.
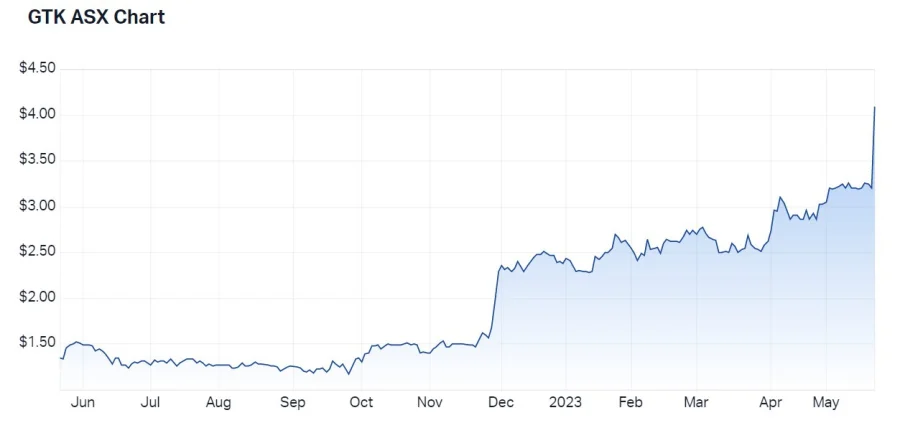
Gentrack share price from ASX
The corollary of utilities not being fast moving businesses is that it's difficult to become established as a supplier to them. That being the problem that Gentrack seems to be solving. The results include: “Revenue: $84.3m – up 47.7% on H1'22, EBITDA $16.0m – up $14.8m over H1'22, Statutory NPAT: $7.9m profit v $5.8m loss in H1'22, Cash: $41.9m – up $14.5m over FY22.”
We could say that Gentrack is over that hump of becoming established as a supplier and now might well be able to enjoy the long term returns from having done so. We shouldn't get too excited though as these results are boosted by one off factors: “Results include substantial one-off revenues, but strong underlying growth means that both FY23 and FY24 revenue guidance have been upgraded to a range of $157m to $160m (from previous guidance of $147m to $150m for FY23 and $150m for FY24)”. It's a creditable performance of course but not wholly - just these half year results - a useful guide to the future. Those projections of revenue are perhaps a better guide than those past results - inflated as they are by some one off factors. But it's also true that the company is expanding its footprint - to Fiji for example.
It is possible to worry a little bit as the CEO makes political commentary about water reforms. But then the people who supply the software that make the industry work might indeed have useful things to say about how the industry works. It's just politicians rarely appreciate being told such things.