Aptamer (LON: APTM) shares are down 51% this morning. This takes the cumulative loss in capital for long term shareholders well over 90% for the past 12 months. This is, as can be imagined, not something making people happy. It's possible to make the economic case - in that sense of the greater economy - that this is just what capital markets are for. To provide the risk capital which allows people to try things out. Some of which will work, many won't. But while that's true at the system level - it is why free market capitalism actually works - that's not a grand comfort to those holding the losses of the so far failures.
The company itself is a “developer of novel Optimer® binders to enable innovation in the life sciences industry” which, to be frank, we're not going to pretend to understand in detail. But then we don't really need to in order to understand what is going wrong at Aptamer. For that's here: “the existing pipeline of new business has taken longer than expected to convert” That is, making actual sales that produce revenue is either more difficult than we expected or taking longer than we'd thought it would. We've seen this complaint in the cybersecurity field just recently, Shearwater and NCC, with about the same effect upon their share prices.
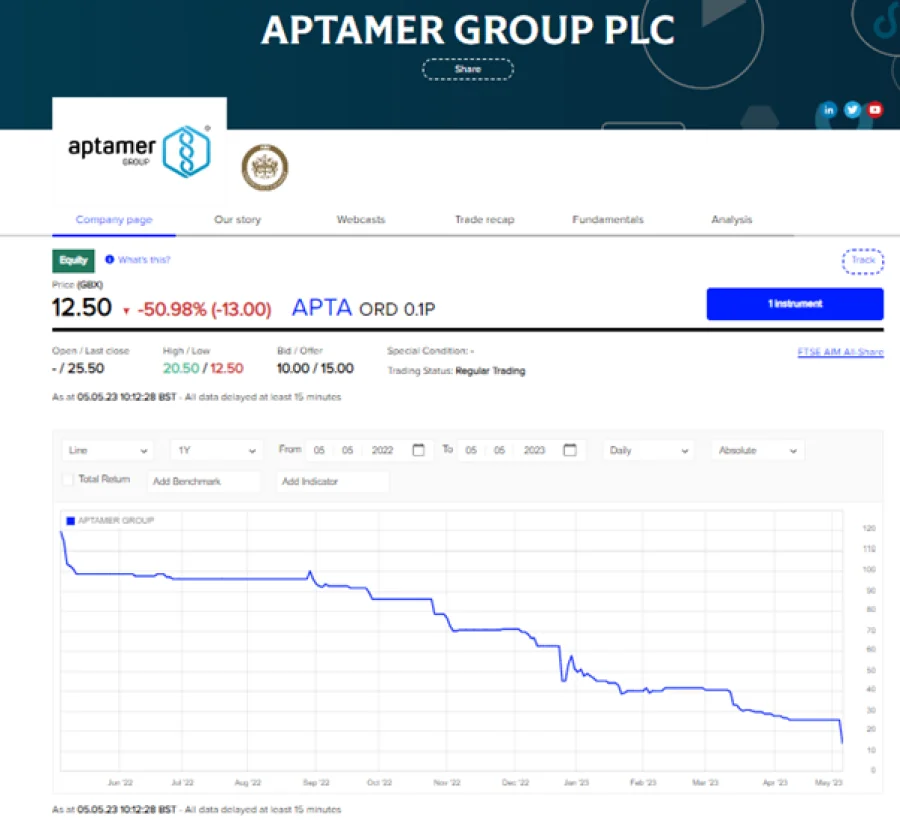
Aptamer share price from London Stock Exchange
The first stage of the problem is that if sales are slow to close then this puts a strain upon working capital in the group. Obviously so - if you've got to wait longer for income then you require more working capital to cover that gap. This then has a knock on effect though. Because it might be necessary to go and find some more working capital to fill that gap. Only so much can be done by reducing expenses after all - some expenses are a necessary component of even being in business at all.
Which is what leads to this: “continuing reduced revenues would mean that the Group would need to raise working capital. The Board is exploring a range of funding options including non-dilutive and dilutive sources to strengthen the balance sheet, which would also provide a stronger negotiating position with potential new business opportunities.” Or, as we could put it, the business is doing badly enough that we might have to ask shareholders for more money. Yes, that'll push a price down 50%.